Before you begin
This story-led series teaches practical concepts in attendance tracking, school management, and business software. Each chapter presents a relatable situation, followed by takeaways and links to explore the tools further.
Important note: Characters, dialogue, and the names of individuals or client businesses in these scenarios—apart from explicitly identified real brands—are fictional or dramatized for educational purposes. This is not a factual account of a real case or an allegation against any person or company. NetCity, Rigi24, Kadrebi and SkolaPlus are real brands and services; their features may evolve.
Chapter Fourteen: The Invoice That Arrived Before the Goods
Sometimes the sales document is ready before the goods have reached the customer.
Nine ten — Two Cartons That Were Not to Be Sold
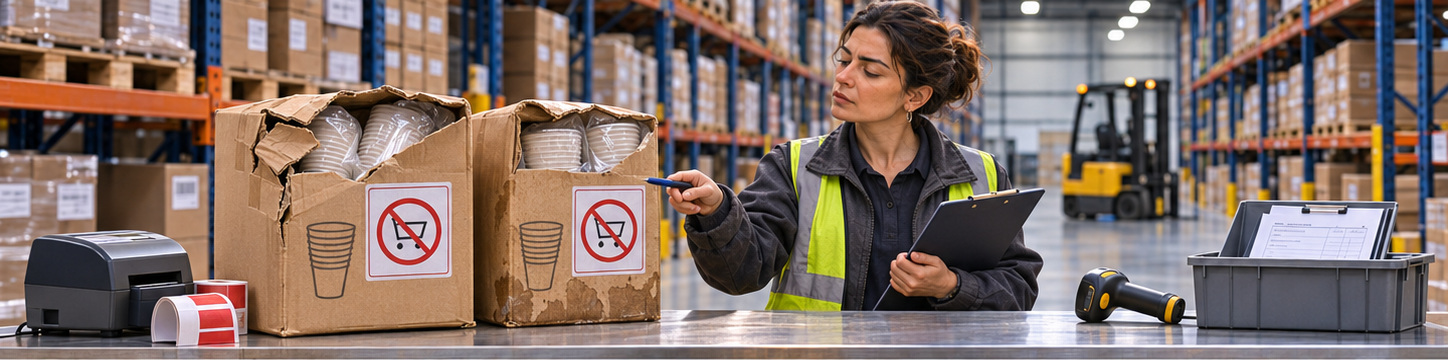
Sopo stood beside the shelving at the far end of the Kutaisi warehouse.
Two damaged cartons of drinking glasses sat on a table.
Beside them stood an old utility trolley that a customer had returned the week before.
Her colleague asked,
“Where should we put these?”
Sopo said,
“First, we need to determine their status.”
“You mean they’re not all returns?”
“No. A return just means the goods have come back. We still need to establish whether they’re in good condition, secondhand, in need of repair, or no longer usable.”
She checked the trolley’s details.
The frame was sound, but one of its wheels was not turning properly.
Sopo said,
“We’ll send this one for inspection and repair.”
Her colleague pointed to the two cartons.
“What about these?”
“We need to see whether the contents are intact.”
An inspection showed that some of the packaging was damaged, but the glasses themselves were intact.
Sopo said,
“So we shouldn’t classify everything inside as scrap just because the carton is damaged.”
Her colleague asked,
“What if some of the goods really are unusable?”
“That quantity needs to be recorded separately, with a clear reason. We can maintain a storage location and records for scrap.”
She opened Rigi24.
Separate locations had been designated within the warehouse structure for secondhand goods, repairs, returns, and scrap.
Sopo continued,
“For secondhand goods, we can also keep details such as serial numbers, physical condition, value, potential selling price, and repair history.”
Her colleague asked,
“What if something gets repaired?”
“Once it’s been inspected and the repair outcome recorded, its status changes. Recoverable scrap has its own process too.”
Then she smiled.
“Just remember, the scrap warehouse isn’t a rubbish bin!”
Her colleague laughed.
“So what if we want a separate location for secondhand goods?”
“We can define a separate location within the warehouse. If we actually need another independent warehouse, we’ll also have to consider the plan’s capacity.”
Sopo glanced at the clock.
“Right, that’s settled. Now we need to get the seventy-carton order ready.”
Her colleague asked,
“That famous order?”
Sopo laughed.
“Yes. The order that taught us eighty cartons can appear in two reports at once!”
Nine forty — One Invoice, Two Opinions
At White Road’s head office, Andro was reviewing the order.
Leila, the sales manager, entered the room.
“Andro, the customer wants us to send over the final invoice.”
Andro asked,
“Have the twelve cartons from Batumi reached Kutaisi?”
“According to the latest update, the shipment is on its way.”
“So not all the goods are ready for delivery yet.”
Leila said,
“But the customer says their finance department needs the invoice.”
Just then Eka, who was responsible for preparing invoices, came in.
“I’ve prepared the pro forma invoice. I’m just waiting for your approval.”
Andro asked,
“The pro forma or the final invoice?”
Eka said,
“The pro forma. I haven’t issued it yet.”
Leila said,
“Well, what difference does it make? We already have the customer’s details and the amount.”
Eka looked at her.
“A big difference.”
Andro smiled.
“I think it’s the finance department’s turn to teach us something today.”
Eka replied,
“Our turn had to come someday!”
Ten o’clock — A Document That Had Arrived Early
Eka set her laptop on the desk.
“Look, the customer requested a quotation for seventy cartons. We’ve specified the price, quantity, and terms of sale.”
Leila said,
“That’s right.”
Eka continued,
“But a pro forma invoice still doesn’t mean a final invoice has been issued. We need to make sure the information is correct and the conditions for issuing it are clear.”
Andro asked,
“So can we send them the pro forma?”
“Yes, after checking it. But it must be clear that the document is a pro forma invoice.”
Leila said,
“The customer thinks sending the pro forma means the goods are ready to ship too.”
Andro replied,
“Then we need to clearly state the preparation and delivery times as well.”
Just then, Leila’s phone rang.
It was the customer.
“Hello, Leila. I’ve received the pro forma invoice. Our finance department just wants to know whether the zednadebi is ready too.”
Leila glanced at Eka.
“Let me check with our finance officer.”
When the call ended, she asked,
“Now what about the zednadebi?”
Eka laughed.
“First, we need to issue the final invoice properly!”
Ten thirty — An Invoice Builder Without a Warehouse
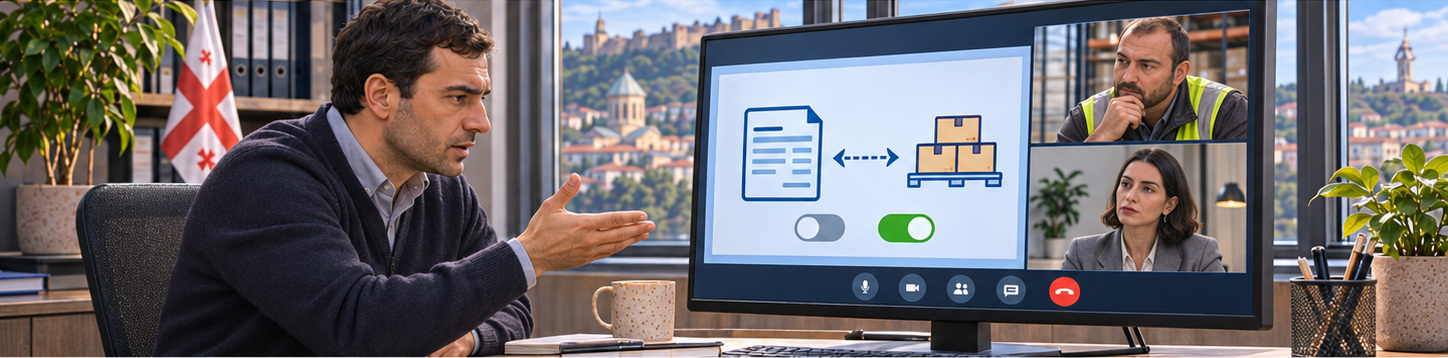
Giorgi and Mari joined the discussion online.
Andro said,
“We’re setting up Rigi24 warehouse management. Now we’d like to activate the invoice builder too.”
Giorgi replied,
“We can look into the requirements. But first, let me clarify something important.”
Andro asked,
“What’s that?”
“The Rigi24 invoice builder is a standalone module. You don’t have to have a warehouse or an online store to use it.”
Eka asked,
“So a service company could use just the invoice builder too?”
Mari replied,
“Yes. A consultancy, a service office, or an educational organization, for example, can issue invoices for its services without having physical goods or a warehouse.”
Leila said,
“Since we have a warehouse, then, we can take advantage of the link between the two modules.”
Giorgi said,
“Exactly. But that link is optional and needs to be configured to suit the company’s operations.”
Andro asked,
“What if we’re only invoicing a customer for packaging services?”
Mari replied,
“That service doesn’t necessarily involve warehouse stock. You can add a service line to the invoice.”
Eka smiled.
“Good. Because I don’t want to have to go looking for a shelf and a barcode before I can invoice a service!”
Nika, who was sitting beside Mari, said,
“So the warehouse is for physical goods, but the invoice builder can be used for both goods and services.”
Mari nodded.
“That’s right.”
Andro said,
“Now let’s get back to the invoice for seventy cartons.”
Ten Past Eleven — Scanning Instead of Typing
Eka was entering the invoice line items.
She searched for the product name in the list.
Two results appeared:
350 ml cup
400 ml cup
Eka said,
“I always have to be careful not to select the second product by mistake.”
Nika asked,
“Don’t you have a barcode scanner?”
Eka said,
“We do. We use it for the warehouse.”
Mari explained,
“The invoice builder also lets you search for goods by name, code, and barcode. Compatible barcode scanners that send the code as keyboard input can make entering items faster.”
Eka picked up the company’s existing barcode scanner.
She scanned the barcode on the product sample.
The corresponding item was identified in the list.
Eka smiled.
“That’s much faster.”
Then she entered the quantity.
70 cartons
Nika said,
“So you don’t have to scan the barcode seventy times?”
Mari replied,
“No. You can identify the item and enter the appropriate quantity. With consecutive scanning, you can also use the line-item entry method, but the operator must check the final quantity.”
Eka checked the unit price.
Then she reviewed the agreed discount and the other invoice details.
Andro asked,
“Does barcode scanning in the invoice builder itself only work when the warehouse is active?”
Mari replied,
“Not necessarily. The invoice builder’s own item catalog can also serve as the basis for product searches. If the warehouse is active and linked, warehouse information is used in the relevant workflow too.”
Eka said,
“So it’s useful for small businesses too.”
Giorgi replied,
“Yes. What matters is that the product details and codes have been entered correctly.”
Twenty to Twelve — The Goods That Had Yet to Arrive
Andro’s phone rang.
It was Davit calling from Batumi.
“Hello, Mr. Andro. The twelve cartons have been dispatched as scheduled.”
Andro asked,
“Do we have confirmation of delivery at the destination?”
“Not yet. The Kutaisi warehouse still needs to record receipt.”
Andro looked at Eka.
“Keep the invoice as a draft for now.”
Eka said,
“All right.”
Leila asked,
“But the customer’s waiting.”
Andro replied,
“We’ll tell them the pro forma invoice is ready, and that we’ll let them know when the final invoice will be issued once the checks are complete.”
Eka showed them the screen.
The invoice was in draft status.
The buyer’s details, items, quantities, prices, and total amount had all been entered.
But it had not yet been issued as a final invoice.
Mari said,
“That distinction is very important. Saving a draft mustn’t be confused with formally issuing a document.”
Nika asked,
“So if Eka has entered something incorrectly, she still has a chance to review it?”
“Yes. She needs to check the details before final issuance.”
Eka laughed.
“I’d rather catch a mistake before issuing it than when the customer calls to ask why the amount is different.”
Twenty Past One — Reserved Stock
A few hours later, Sopo confirmed receipt of the twelve cartons from Batumi.
Andro checked the report.
The stock available to allocate to the order was now clear.
Fifty-eight cartons from Kutaisi’s previously available stock.
Twelve cartons from the shipment that had arrived from Batumi.
Total: seventy cartons
Eka asked,
“Shall we issue the invoice now?”
Andro said,
“After the final check, yes.”
Mari explained,
“When an invoice is linked to warehouse stock, it needs to be clear at what stage the goods are reserved and when the actual stock release is recorded.”
Leila asked,
“Does that mean seventy cartons leave the warehouse when the invoice is issued?”
“Not necessarily. Reserving stock and actually handing over the goods are two different stages.”
Nika said,
“So if we prepare the goods for dispatch after reserving them, the stock shouldn’t be deducted again when the stock release document is issued.”
Mari replied,
“Exactly. Each operation must affect stock only once.”
Andro said to Eka:
“Then check the details again. After that, we’ll issue the invoice.”
Eka checked the customer’s name and legal details.
Then she matched the items, quantities, and prices against the order.
Once the authorized person had approved it, the final invoice was issued.
Leila breathed a sigh of relief.
“At last!”
Andro laughed.
“Yes. And now the accounting work can finally begin!”
Five Past Two — The Accountant Who Hadn’t Been Told Yet
Eka sent Medea the invoice number.
Medea was the company’s accountant and handled most tax matters from her own office.
A few minutes later, she called.
“Eka, does this invoice need a zednadebi?”
Eka said,
“Yes.”
Medea asked,
“Then why haven’t you logged the request in the accounting workflow?”
Eka paused for a moment.
“I sent you the invoice number.”
Medea replied,
“The invoice number isn’t enough. It needs to be clear which document you need, what the transaction details are, and what stage the request has reached.”
Eka said,
“You’re right.”
Medea continued,
“If you just send numbers through a messaging app, one of the invoices could get lost among the messages.”
Eka laughed.
“I should send that line to Giorgi. I think he’s run into that very problem before!”
Twenty Past Two — The Zednadebi
Eka opened the invoice’s tax documents section.
Andro stood beside her.
“What exactly do we need to do?”
Eka said,
“This invoice needs a zednadebi. We’ll log a request for the accountant.”
Andro asked,
“Is a zednadebi the same as our invoice?”
Medea, who was still on the call, replied,
“Not exactly. In Georgia, a ზედნადები, or zednadebi, is a document relating to the movement and transport of goods within tax and commercial procedures. It must be prepared in accordance with the applicable regulations.”
Andro asked,
“So does Rigi24 issue it directly in the tax system?”
Medea explained,
“No. This is where the accounting request is logged and tracked. Issuing and registering the document through the legally required process and the relevant system is the accountant’s responsibility.”
Eka said,
“So we send you the invoice from Rigi24 and specify that a zednadebi is required.”
Medea replied,
“Yes. Once the work is done, we record the outcome and the document details as well, so its status is clear.”
Andro asked,
“Do we have to send the request manually every time?”
Eka said,
“There’s also an option to automatically send requests for finalized invoices requiring a zednadebi to the accounting workflow. But first, the company settings and the accountant responsible need to be configured correctly.”
Andro smiled.
“Good. I just don’t want any invoice moving to the next stage without the necessary checks.”
Medea replied,
“Exactly. Sending a request to the accountant is not the same as having the accounting work completed.”
Three O’Clock — A Document with a Georgian Name
Leila came into the office.
“Mr. Andro, the customer wants another document too.”
Andro asked,
“What document?”
Leila held up the paper.
Written on it was:
Delivery and Acceptance Certificate
Andro looked at the text.
“What is it now?”
Eka replied,
“It’s a certificate of delivery and acceptance for work or goods. The customer wants the corresponding document once they’ve received the order.”
Andro said,
“Does that mean we have to type up another form from scratch?”
Eka smiled.
“Not necessarily.”
She opened the section for the delivery and acceptance certificate.
The details from the issued invoice were available.
The seller’s and buyer’s details and the transaction amount formed the basis for preparing the document.
Eka said,
“This part is a real help. We don’t have to retype the information we already have on the invoice every time.”
Andro asked,
“So it generates the document itself?”
“We can prepare the document using the invoice details. The parties’ and signatories’ details are also suggested if the necessary information is available. Then we need to check the date, details, and delivery terms before generating the document.”
Leila asked,
“So can we sign it right now?”
Eka said,
“No. The goods haven’t been delivered to the customer yet.”
Andro laughed.
“At last, someone who cares even more than I do about actual delivery!”
Eka replied,
“The invoice may have been issued, but the acceptance certificate has to reflect what actually happened.”
Medea also stressed,
“And generating a PDF does not mean the other party has actually approved or signed it.”
Andro nodded.
“Good. Then we’ll prepare the document, but carry out the next steps in line with the actual delivery.”
The Next Day — A Signature That Had to Wait
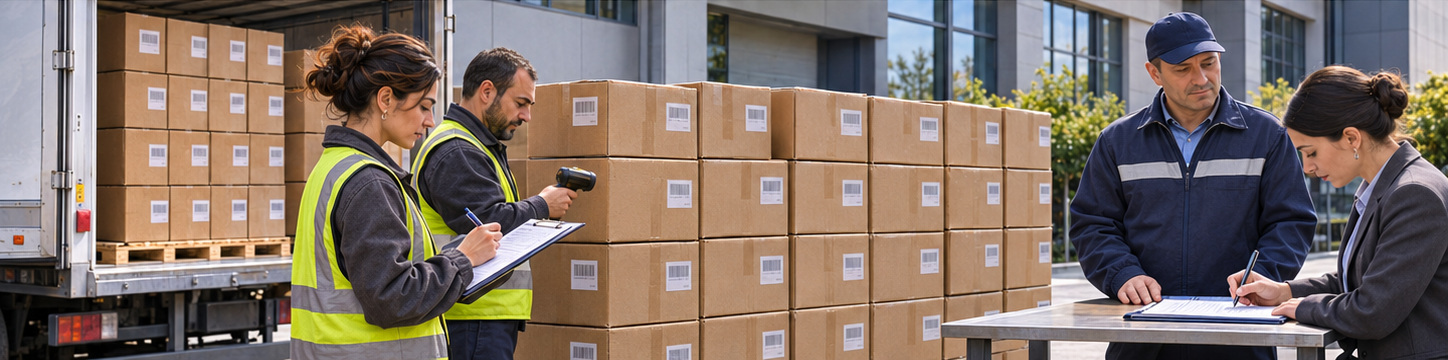
The shipment of seventy cartons arrived at the customer’s premises.
The person responsible for the delivery presented the documents accompanying the goods.
The customer’s representative said,
“Before signing, we’ll check the number and condition of the cartons.”
The driver replied,
“Of course.”
The cartons were counted.
The count was correct.
The packaging was also checked for visible damage.
The customer’s representative said,
“We’ve received seventy cartons.”
The relevant documents were then checked and approved through the agreed procedure.
At the White Road office, Eka reviewed the delivery confirmation.
Andro asked,
“Is everything done?”
Eka replied,
“Delivery has been confirmed. Now we can follow up on the acceptance document too, based on the actual paperwork.”
Leila said,
“Good. The customer is waiting for that document for their finance department.”
Eka reviewed the generated document.
The parties’ details, the amount, and the invoice information were correct.
The document was sent for the necessary approval and signature.
Andro looked at the screen.
“So this time we had an invoice, a delivery document, and an accounting request.”
Eka said,
“Yes. But each follows its own process.”
Eleven Fifty — The Payment That Hadn’t Arrived in Full
Medea called Eka.
“Have you checked the customer’s payment?”
Eka said,
“Part of the amount has come through.”
“Then don’t mark the invoice as paid in full.”
Eka replied,
“I know. I’ll record the partial payment and leave the remaining balance open.”
Andro asked,
“So we can see how much has been paid and how much is left?”
Eka said,
“Yes. When we record payments correctly, we can track the invoice status and the outstanding balance.”
Andro said,
“So I don’t have to write on a scrap of paper that someone’s paid half the money anymore!”
Medea laughed.
“Provided, of course, that every payment is reconciled with the actual bank information and the relevant supporting documents.”
Andro replied,
“I know that condition by heart now.”
One Fifteen — The Invoice That Came Back Every Month
Eka was reviewing the company’s financial records.
Medea asked,
“What happened with that customer who uses your packaging services every month?”
Eka sighed.
“I have to prepare their invoice from scratch every month.”
Medea said,
“We can use the recurring invoice features.”
Eka asked,
“You mean a final invoice gets sent to the customer automatically every month?”
“No. Drafts can be prepared for recurring periods, then reviewed and approved before they’re issued.”
Eka said,
“That’s much better. The amount changes some months.”
Medea replied,
“Exactly. Preparing a draft isn’t the same as issuing a final invoice and sending it to the customer.”
Andro, passing by the desk, said,
“The less repetitive work you have, the more time you’ll have to review the important things.”
Eka smiled.
“Provided you don’t find us a customer with seventy cartons of glasses every day!”
Three Twenty — Accounting That Hadn’t Been Forgotten This Time
Medea was sitting in her own office.
She was reviewing the accounting requests.
White Road’s invoice appeared on the list.
The zednadbi request was clearly identified.
Medea checked the necessary information and carried out the relevant work through the legally required procedure.
She then recorded the result and the document details in the tracking history.
Eka checked the status.
This time, she didn’t need several calls and messages to ask,
“Have you issued the zednadbi?”
Andro said,
“So the accountant tracks her part of the work within this same process too.”
Eka replied,
“Yes. With clearly defined access and responsibilities.”
Andro asked,
“And if a document needs correcting?”
“The request has to be reviewed and the necessary information corrected. What matters is that its status doesn’t remain unclear.”
Andro nodded.
“That’s exactly what I wanted.”
Four Forty — One Company, Several Different Needs
At the NetCity office, Giorgi was reviewing the setup results with Mari.
Nika asked,
“So White Road has three modules now?”
Giorgi said,
“They’re setting up and evaluating the inventory and invoice builder features. They’re making a separate decision about the online store.”
Nika said,
“But if a company only wants the invoice builder, it can use it without inventory.”
Mari replied,
“Yes.”
“If it has a barcode scanner, it can use it to enter items quickly.”
“With a compatible workflow and hardware, yes.”
“If it also has inventory, it can configure the connection between invoices and stock.”
“That’s right.”
“Then send the accountant a request for a zednadbi.”
Giorgi said,
“Yes. But don’t confuse actually issuing the document in the government system with logging a request in Rigi24.”
Nika continued,
“And if the customer wants an acceptance and handover certificate, it can use the invoice information to prepare the document.”
Mari smiled.
“Well done.”
Nika said proudly,
“I think I can skip reading any new articles today.”
Giorgi said,
“Actually, we have several articles on accounting and recurring invoices that you haven’t read yet.”
Nika sighed.
“I wish we had a module that would read the articles for me!”
From behind his monitor, Morteza said,
“AI can help you understand the material. But you can’t hand over all responsibility for learning to it.”
Mari laughed.
Nika said,
“Another suggestion of mine rejected.”
Five Fifteen — Three Different Events
Andro reviewed the day’s final report.
The seventy-carton order had been fulfilled.
The final invoice had been issued.
The request for a zednadebi had been followed up.
The delivery and acceptance document had also been prepared and approved through the appropriate process.
The customer had not yet paid in full, but the amount received and the outstanding balance were clear.
Andro said to Eka,
“I thought once we’d found the goods, the job was done.”
Eka laughed.
“Actually, that’s where our work begins.”
Andro said,
“Now I understand better why an order, an invoice, and a delivery shouldn’t be confused with one another.”
Eka asked,
“Would you like me to write that on the wall?”
Andro replied,
“No. Record it in the system so we remember next time!”
They both laughed.
Five Forty — The Package That Had Been Delivered
At the NetCity office, Nika was ready to leave.
Giorgi picked up his phone.
A new message had arrived from Archil, the owner of House of Color.
Giorgi read the message.
Then he read it again.
Mari asked,
“What’s happened?”
Giorgi said,
“Archil has a question about one of the online orders.”
Nika asked,
“An invoice again?”
“No. Shipping this time.”
“What happened?”
Giorgi replied,
“The customer says the package still hasn’t arrived.”
Nika said,
“Then the courier’s probably running late.”
Giorgi showed him the phone.
Archil’s message read:
“The order status shows the package as delivered. But the customer says they haven’t received anything.”
Nika was silent for a few moments.
Then he said,
“So the package has been delivered, but the customer hasn’t received it?”
Mari replied,
“For now, all we have are two conflicting reports. We need to find out who it was delivered to and on what basis delivery was confirmed.”
Nika put his bag back on the desk.
“I don’t think tomorrow’s going to be a quiet day either.”
Giorgi laughed.
“Since when have you wanted a quiet day?”
Nika said,
“Since chapter one!”
Tools and further reading
Explore the real services and related guidance behind this chapter:
Learning note: examples are illustrative, not a substitute for reviewing real records.