Inventory Returns Management: Partial Returns, Damaged Goods and Stock Reconciliation
Practical guide to full and partial inventory returns, damaged stock, financial refunds, warehouse movements and accurate sellable balances.
Practical guide to full and partial inventory returns, damaged stock, financial refunds, warehouse movements and accurate sellable balances.
Why inventory returns management is a separate operational discipline
Inventory returns management is not a single action and it is not the same as “giving money back.” In a retail or warehouse environment, a return touches several different business objects: the customer request, the physical receipt of the goods, the inspection result, the inventory adjustment, the accounting decision, and the payment outcome. If these are blended together, teams quickly create duplicate stock entries, wrong credit amounts, and confusing customer records.
For a business using Rigi24 as an operational system for items, warehouses, locations, stock counts, stock movements, repair, damage, and scrap, the safest approach is to treat returns as a controlled workflow with separate checkpoints. That is especially important in a network-equipment warehouse in Tbilisi, where routers, switches, power supplies, and accessories may share similar packaging but differ by serial number, warranty state, or sale unit. A return may involve one invoice line, several distinct SKUs, or only part of a quantity. The operational question is never simply “did it come back?” but “what exactly came back, in what condition, and what downstream action is justified?”
The six independent stages in a return workflow
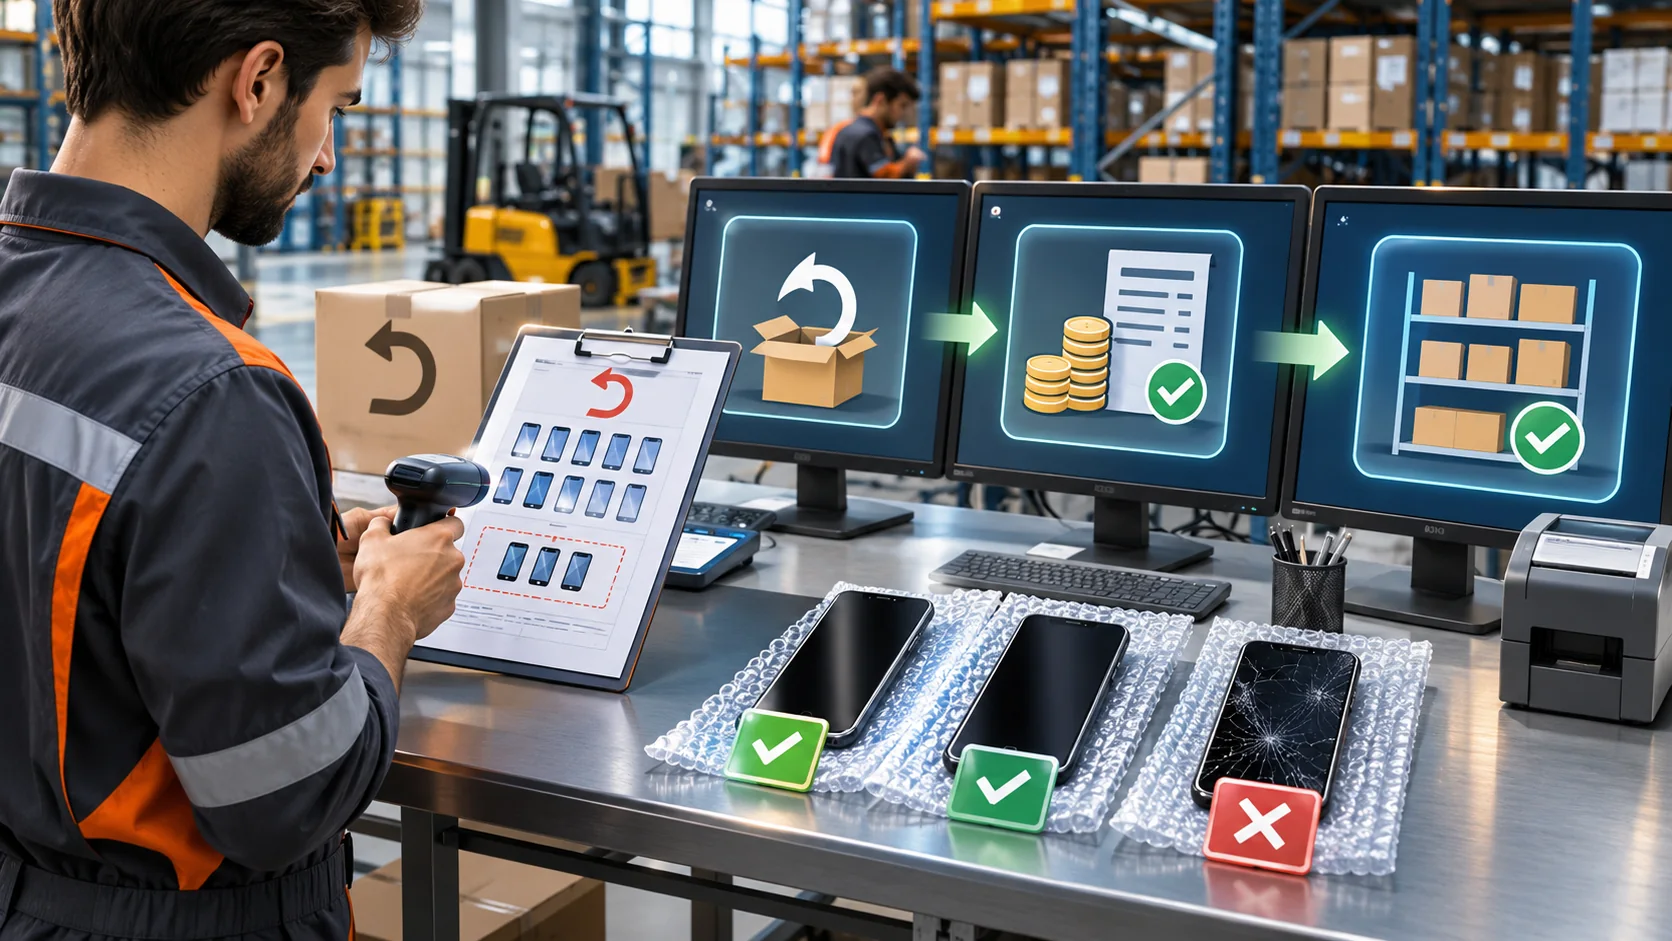
A robust return process has six independent stages. They may happen close together, but they should not be merged into one event.
- Request to return: the customer or internal team asks for a return, replacement, or correction.
- Physical receiving: the item arrives at the receiving desk or warehouse intake point.
- Item inspection: staff verify identity, condition, completeness, and return eligibility.
- Stock movement: inventory is moved to available stock, repair, damage, scrap, or quarantine, depending on inspection.
- Credit note: the invoice is adjusted or reversed in the accounting or sales records.
- Actual payment refund: cash, card reversal, bank transfer, or other payment action is executed.
These stages can produce different outcomes. For example, a customer may request a return and be approved, but the goods may never arrive. Or the goods may arrive, but one unit is damaged and only two are re-stockable. Or a credit note may be issued while the payment refund remains pending because the card processor or finance team has not completed it yet. Best practice is to treat each stage as a separate operational state so that teams can track what happened, what remains open, and where value is still exposed.
Request to return is not the same as receiving the goods
The return request is the beginning of the process, not the end. At this stage, the customer explains the issue: wrong item, dead on arrival, excess quantity, packaging damage, or change of requirement. In a Tbilisi office-supply or network-equipment business, the request may also come from a field engineer or a branch location rather than a consumer. The purpose of this stage is to collect enough information to decide whether the return should be authorised and how it should be handled later.
A request should capture the invoice number, SKU or item name, quantity requested for return, reason code, and any promised evidence such as photos or serial numbers. However, a request does not prove that the item has physically come back. Teams must avoid writing off stock, creating a credit note, or refunding money before the physical item is in hand or the business has a confirmed exception process. A pending request can be approved, rejected, partially approved, or redirected to repair or exchange depending on policy.
Receiving desk checklist for a physical return
When the goods actually arrive, the receiving desk needs a strict checklist. This prevents mix-ups between the original sales record and the physical item presented for intake.
- Confirm the original invoice or sale reference.
- Collect proof of purchase if the return is linked to a customer claim.
- Verify item identity against SKU, barcode, serial number, batch, or model.
- Record photos of the item and packaging before opening or testing.
- Stamp the intake timestamp to establish when custody changed.
- Document the reason for return as stated by the customer and as observed by staff.
- Log the customer communication so sales, warehouse, and finance all see the same narrative.
In practice, the receiving desk should also check whether the returned item belongs to the original sale at all. A box with the right model number but the wrong serial number can be a swapped item, a counterfeit claim, or a simple mix-up. A barcode alone is not enough when multiple units of the same product exist. If the item is network equipment, serial tracking is often essential for matching the physical unit to the invoice line and for deciding whether it belongs in repair, usable stock, or scrap.
Return authorisation versus physical warehouse receiving
Return authorisation is an approval to accept a potential return under defined conditions. Physical warehouse receiving is the actual intake of the goods. These are not the same. A business should create a pending or quarantine area before inspection, even if the return is pre-approved, so the item does not accidentally enter available stock.
This separation matters because returned goods may be incomplete, damaged, dirty, or simply different from what was promised. If a warehouse immediately books them into saleable stock, stock counts become inflated and warehouse workers may reship defective items. The quarantine area can be a physical shelf, cage, or location in the warehouse system reserved for items that have not yet been cleared. In an operational workflow, the item moves from “received pending inspection” to a final location only after the condition is known.
Worked example: ten devices sold, three returned
Consider a hypothetical invoice in a Tbilisi electronics store for 10 network devices at 180 GEL each, plus 18% VAT included in the final price for simplicity of illustration. The total invoice value is 1,800 GEL before tax treatment in the internal example. The customer later returns 3 units. On inspection, two are in good resale condition and one is damaged.
Let us allocate the quantities correctly. The original invoice line showed 10 sold units. The return request covers 3 units. That does not mean the full invoice is returned; it is a partial quantity return on one invoice line. If the business later needs to refund or credit only the returned units, the operational record should reflect exactly 3 units returned, not 10.
Financially, the business can only treat the units that physically qualify as accepted return stock or accepted return loss. If 2 units are good and 1 is damaged, the stock movement should separate them:
- Two units move from pending/quarantine to usable inventory after inspection.
- One unit moves to damage or scrap, or to repair if the business has a repair workflow and the item is eligible.
- The customer credit or refund should align with the return policy and the accepted return quantities, not with the total original sale.
If the purchase price per unit was 120 GEL and the sale price per unit was 180 GEL, the inventory system and finance team should not confuse cost with selling price. The stock movement affects quantities and valuation at cost, while the credit note reflects sales value and tax treatment according to the invoice rules in use. For example, if only the two good units are accepted for resale return and the damaged unit is accepted as a non-resellable return, the business may still issue a customer credit for all three units if policy allows, but it must separately classify the damaged unit into damage or scrap rather than available stock. If policy only credits saleable returns, then the damaged unit may be rejected or credited differently. The key point is that the physical condition and the financial allocation are related but not identical.
Why full invoice return, selected lines, and partial quantities are different events
A full invoice return means every item on the invoice is being reversed. A selected invoice-line return means only some specific products on the invoice are coming back. A partial quantity return means only a portion of a line quantity is returned. These are not interchangeable.
Imagine a network-equipment invoice with three lines: 4 routers, 5 patch cables, and 1 rack switch. If the customer returns only 2 routers, that is a partial quantity return on one line. If they return the 5 patch cables but keep the routers and switch, that is a selected-line return affecting one full line. If they return all 10 items, it is a full invoice return. These distinctions matter because they affect stock movements, tax adjustments, payment refunds, and customer communication. Treating all three as the same event leads to duplicate reversals, wrong line-level quantities, and inventory mismatches.
Identifying returned items without double counting
To avoid double counting, the return record should identify the item at the most specific level available. That may include SKU, barcode, serial number, batch number, sale unit, purchase cost, tax details, and the exact invoice line reference. Each field solves a different problem.
- SKU: identifies the product type.
- Barcode: helps scan the unit quickly, but may not uniquely identify the individual item.
- Serial number: identifies a specific physical unit when available.
- Batch: matters for grouped inventory or lot tracking.
- Sale unit: defines whether the item was sold as piece, box, set, or pack.
- Purchase cost: supports valuation and stock accounting.
- Tax: supports correct invoice adjustment.
- Invoice line identification: connects the return to the original sale line and quantity.
Without this granularity, a team may accidentally return the same unit twice, especially if one return is entered by customer service and another by warehouse staff. Best practice is to record the item once at the physical intake stage and then carry that identity through inspection, stock movement, and financial settlement.
Failure cases managers should expect
Returns fail in predictable ways, and managers should plan for them. One common failure is when promised items arrive in a different condition than recorded in the request. The customer may say “unused, unopened,” but the box may be torn, missing accessories, or have clear installation marks. Another failure case is partial arrival: the customer promised to return three devices but only one arrives on the first visit. That means the request remains open for the other two units, and the system should not close it prematurely.
Another frequent problem is mismatch between invoice and physical item. A customer may bring back the correct product family but an incorrect serial number. In a warehouse setting, that could happen if devices were swapped between projects or if the customer sends back a unit from another branch. The receiving desk should quarantine the item, flag the mismatch, and wait for confirmation before any inventory release.
A further failure case is premature stock movement. If a worker puts the returned device directly into usable stock before inspection, the inventory count becomes inaccurate. If a finance clerk issues a credit note before the item is received, the customer may receive a refund for something that never came back. These are different operational errors, and both should be prevented by clear status separation.
Checklist for a safe operational sequence
Managers can use the following sequence as a practical control list for returns handling.
- Receive and log the return request separately from the physical item.
- Verify invoice reference, SKU, and quantity requested.
- Authorise or reject the return based on policy.
- When the goods arrive, assign them to a pending or quarantine location.
- Record intake timestamp, photos, and item identity details.
- Inspect condition and decide usable, repair, damage, scrap, or reject.
- Create the correct stock movement only after inspection.
- Issue a credit note only for approved quantities and amounts.
- Process the actual refund only after finance or payment reconciliation.
- Close the case only when all stages are complete and matched.
This workflow is especially useful in a mixed online-store and invoice environment, where an online order request may exist alongside a sales invoice record. The important discipline is to keep each source document separate until the business deliberately links them. That prevents duplicate updates and makes it easier to explain, review, and audit each return case with clarity.
Disposition Decisions After a Return: What the Item Becomes Next
Inventory returns management is not only about taking something back from a customer. The more important operational question is what the item becomes after it re-enters your control. A returned unit may be immediately sellable, open-box but still resellable, damaged beyond resale, suitable for repair, eligible for a supplier return, or so uncertain that it should be quarantined for further review. In a disciplined workflow, the condition decision must happen before any stock count is updated, because stock should be condition-specific rather than treated as one undifferentiated pool.
For a retail business in Tbilisi selling routers, Wi-Fi access points, and consumer electronics, this distinction matters every day. A customer may return a sealed router because they ordered the wrong model. Another may bring back a switch with missing accessories. A third may return a device with cracked casing and no power. These are not operationally equivalent. If you place all three back into the same on-hand bucket, your available-to-sell number becomes misleading and so does your promise to the next buyer.
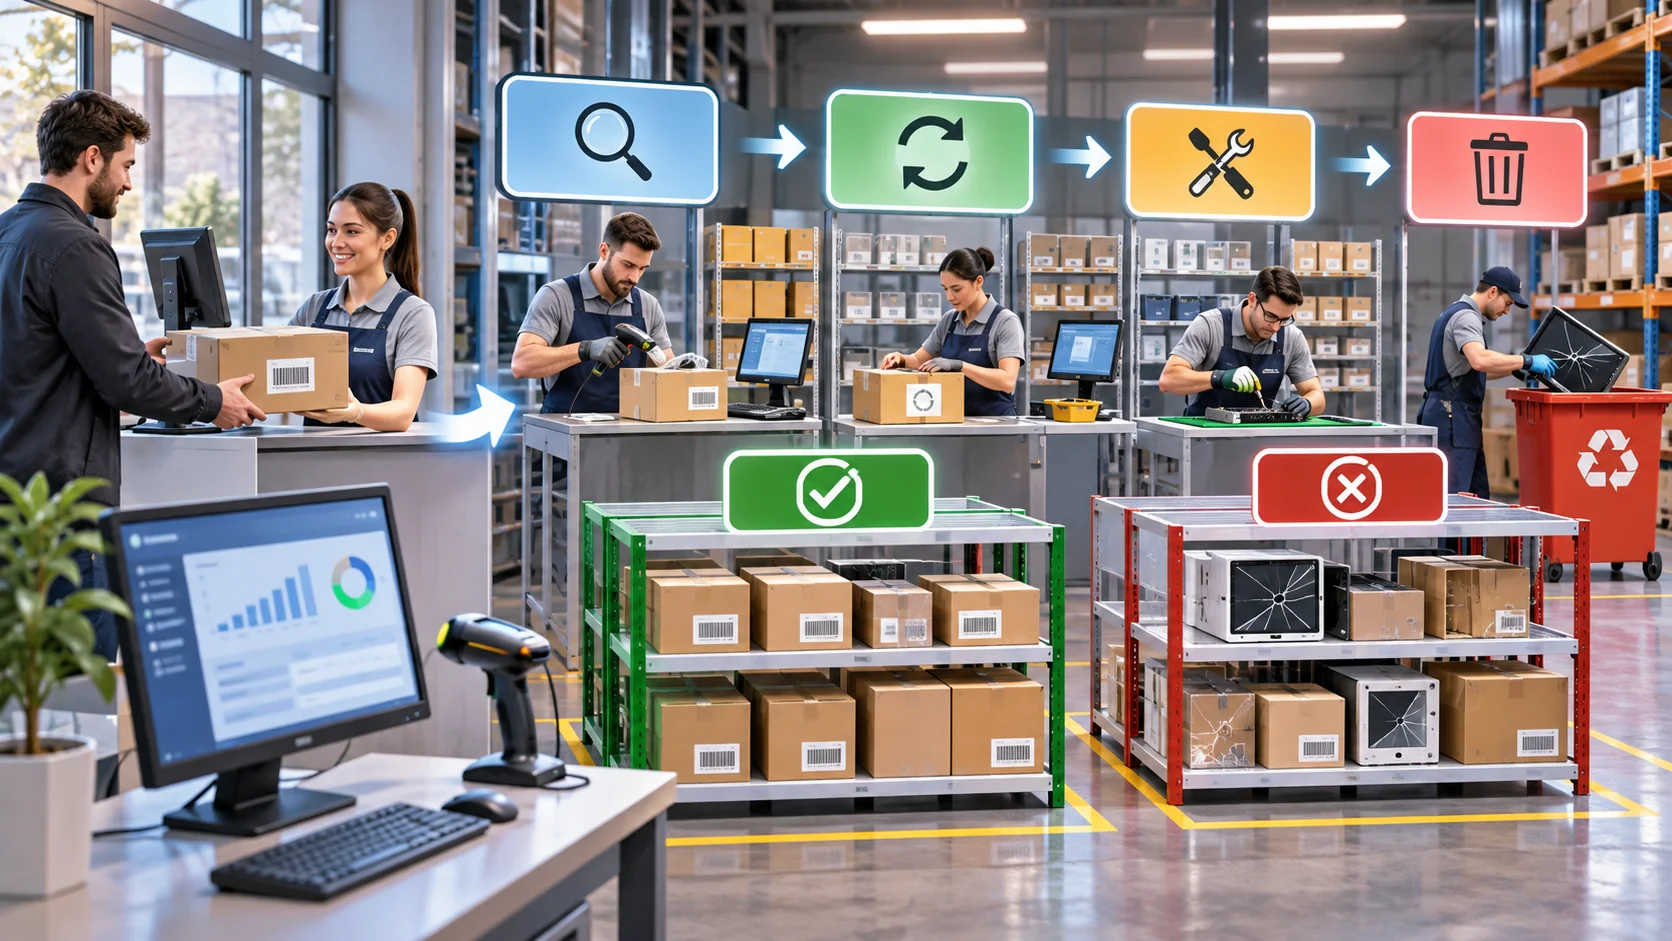
A practical disposition matrix usually starts with a physical inspection and ends with one of several documented outcomes. The outcome should be tied to an item condition code and a movement type, not to a vague note in a comment field. This supports later review, serial tracking, and reconciliation between warehouse, repair, and sales records.
| Disposition | Typical condition | Stock effect | Operational follow-up |
|---|---|---|---|
| Sellable | Unopened, complete, no defects | Increase good stock | Return to shelf or fulfill pending demand |
| Open-box | Opened but complete and functional | Increase open-box stock | Price review, relabel, segregate |
| Damaged | Broken, scratched, missing critical parts | Increase damaged stock | Assess repair, claim, or scrap |
| Repair | Serviceable after technical work | Move to repair queue | Track technician status and turnaround |
| Supplier return | Defect, warranty issue, or inbound mismatch | Move out of saleable stock | Prepare outbound return to supplier |
| Quarantine | Unclear identity or safety concern | No saleable increase yet | Hold for investigation |
| Scrap | Nonrecoverable | Remove from usable inventory | Document disposal or destruction |
How to Classify Stock by Condition, Not by Memory
The most common return-processing failure is to update quantity before the item is inspected. The better sequence is: receive the physical item, match it to a source document, inspect condition, choose disposition, then apply the inventory movement. If a business receives two good items and one damaged item, it should not create one general return quantity and sort it out later. That approach forces staff to reverse or recategorize stock after the fact and increases the chance of double counting.
Condition-specific stock is especially important for network equipment and electronics. A sealed access point may remain sellable. The same model with a broken seal and a missing mounting kit may be open-box if the main unit works and accessories are replaceable. A unit with a burnt power supply may be repairable. A unit with liquid damage should often be quarantined immediately, because powering it on can create safety risk and can also complicate warranty review.
Use a disciplined check sequence:
- Verify SKU, model, and serial number if applicable.
- Inspect packaging, seals, ports, casing, and labels.
- Confirm accessories against the expected contents list.
- Test power-on behavior when safe to do so.
- Choose one disposition only, even if the item has multiple issues.
- Record the reason code, inspector, timestamp, and source document reference.
When staff skip this sequence, a store may count damaged stock as available. That creates overselling risk, especially if the same item is simultaneously listed in an online-store module and referenced in an invoice module. The operational rule should be simple: stock may only be made available in the condition bucket where it can truly be sold.
On-Hand and Available-to-Sell: An Explicit Return Example
Consider a hypothetical Georgia/Tbilisi electronics shop with a router model that has the following starting position before returns are processed:
- Good stock on hand: 10 units
- Reserved for pending orders: 3 units
- Damaged stock: 1 unit
Now three returns arrive from customers: 2 units are returned in good condition, 1 unit is damaged. The correct result depends on condition. The two good units should increase good on-hand stock. The damaged unit should increase damaged stock, not saleable stock.
After processing the physical items correctly, the updated counts become:
- Good stock on hand: 12 units
- Reserved for pending orders: 3 units
- Damaged stock: 2 units
Available-to-sell is calculated from good stock minus reservations, assuming no additional operational hold exists. In this example, available-to-sell is 12 minus 3, which equals 9 units. The damaged items are not part of available-to-sell. They are tracked separately because they are not presently fit for sale.
This is the key operational lesson: on-hand is not a single number if your business cares about condition. Good stock on hand and damaged stock on hand are different realities. A dashboard that collapses them into one figure can look healthy while the shelf is actually unhealthy. For managers, the useful view is often a matrix by warehouse, location, and condition, because that is what prevents false replenishment decisions.
Credit Memo, Refund, Exchange, and Store Credit: Separate Decisions
Physical return and financial reversal are related but not identical. A returned item may trigger a credit memo, a refund, an exchange, store credit, or no immediate financial action at all, depending on the business policy and the transaction structure. These concepts should never be treated as interchangeable.
- Credit memo: a document that reduces the amount owed or recorded against the original sale.
- Refund: money returned to the customer through the payment path or accounting process.
- Exchange: the original item is returned and replaced by another item, often with price difference settlement.
- Store credit: a non-cash balance or voucher-like value that the customer may use later, if your policy allows it.
A company should not assume any local tax or legal obligation in this article; those requirements depend on jurisdiction and professional advice. Operationally, however, the control principle is stable: financial reversal should map precisely to the return event that justifies it. If a customer exchanges a damaged access point for a different model, the return of the damaged unit does not automatically mean a cash refund is appropriate. The sales difference, restocking logic, and customer entitlement must be evaluated separately.
One common failure case is issuing a refund first and then later processing a return receipt again from a second user action. That can create both a duplicate credit and a duplicate stock increase. A safer workflow is to use the original document reference as the anchor for both the stock movement and the financial adjustment, so the system can detect that the event has already been handled.
Partial Exchanges Without Double Credits or Duplicate Stock
Partial exchange scenarios are among the most error-prone return cases in retail. Imagine a customer in Tbilisi bought two items: one high-end router and one access point. They return only the router, which is slightly open-box but still functional, and ask to exchange it for a lower-priced model while keeping the access point. The warehouse must process only the returned line, not the entire invoice.
The workflow should be divided into four controlled steps:
- Identify the exact line being returned and the quantity on that line.
- Inspect the item and determine disposition.
- Create one inventory movement for the return disposition and one sales movement for the replacement item, if any.
- Settle any price difference through the finance process once, and only once.
If the returned router is accepted as open-box stock, its quantity should increase only in the open-box bucket. If the replacement device leaves the warehouse, the good-stock bucket should decrease once. The risk is that a user might click “process return” twice or a webhook from a payment or order system might arrive twice. Without a control mechanism, the exchange line could be credited twice and the replacement stock could be added or deducted twice.
A robust operational design uses a document reference or idempotency key tied to the original sale line and the return event. If the same request comes again, the system should recognize it as already processed and not repeat the movement. Even if your software stack is simple, this is best-practice evaluation territory: ask whether duplicate-click protection, event deduplication, or reference-based locking is present before trusting automation to handle financial and inventory consequences.
Supplier Returns and Customer Returns Across Two Warehouses
Supplier returns and customer returns are both reverse flows, but they are not the same operationally. A customer return moves goods from a sale history back into your control. A supplier return moves goods from your controlled stock back out to the vendor. The paperwork, ownership assumptions, and warehouse movements differ.
Consider a two-warehouse scenario in Georgia. The Tbilisi retail warehouse receives a customer return of a defective network switch. The item is inspected, found to be damaged, and judged eligible for supplier return rather than repair. The process might look like this:
- The retail warehouse creates a damaged return intake record.
- The item is placed in quarantine or damaged holding.
- A cross-location transfer moves it from the retail warehouse to the central service warehouse.
- The service warehouse performs final check and prepares the supplier return shipment.
- The outbound supplier return reduces stock in the service warehouse, not in the retail warehouse again.
Why does the second warehouse matter? Because if the same item is counted down at the retail warehouse and again at the service warehouse without a proper transfer record, stock can disappear twice. The item is physically moving once, but the system may think two separate removals happened. Cross-location returns should therefore use distinct source and destination locations, each with a traceable movement reason.
A useful control question is: “Where is the item now, and in what status?” If the answer is “in quarantine at warehouse A” or “in repair queue at warehouse B,” then that status should govern the next movement. Supplier return paperwork should never be created from a vague assumption that a customer return can automatically be sent back upstream. It must be reviewed, aggregated if necessary, and approved by a responsible operator.
Inspection and Quality Assurance for Electronics
Electronics returns demand more than a quick visual glance. Broken seals, accessory shortages, and warranty-sensitive defects all affect the correct disposition. For routers, switches, power supplies, monitors, and similar goods, the inspection should check whether the seal is intact, whether serial labels match the box, whether all listed accessories are present, and whether the device powers on safely.
A practical quality assurance checklist includes:
- Verify outer carton and internal packaging condition.
- Check for broken seals or evidence of prior installation.
- Confirm cables, brackets, manuals, and adapters.
- Test basic power and indicator behavior where appropriate.
- Record defects with photos or notes in the case file, if your operation uses them.
- Separate warranty-related observations from cosmetic damage.
Broken seals do not automatically mean a product is damaged, but they may change commercial value or resale class. A missing accessory may mean the device is still functional but not complete. Warranty-related goods often require a different path: repair evaluation, supplier escalation, or customer service review. The important part is that the physical result and the financial result remain distinct. An item can be physically returned yet still be held in quarantine until its quality status is resolved.
Traceability: GTIN, EPCIS, and Why a Barcode Scan Is Not Enough
Traceability is often misunderstood. A barcode scan identifies an item identifier, but the scan itself does not prove that stock physically changed location, condition, or ownership. That proof comes from the controlled inventory event. In many environments, GTIN is the identifier used to identify a trade item, while EPCIS is a standard for communicating event data. These are not the same thing as “we scanned something, therefore inventory changed.”
For operations managers, the principle is straightforward: a scan is an input, not a conclusion. If a return is scanned at the counter but not yet inspected, the item is still merely received, not necessarily resellable. If a serial number is scanned and the item is set aside for repair, that repair state should be recorded as an event, not inferred later from a note.
This matters in Rigi24 evaluation and workflow design as well. Rigi24 has inventory items, warehouses, locations, stock counts, stock movements, repair, damage, and scrap concepts. Those are the building blocks you should map to your return process. However, do not assume that any online-store or invoice capability automatically synchronizes returns, partial line returns, payment reversals, or serial-level event deduplication unless you have verified it. Best practice is to define the workflow externally: scan, inspect, decide, move, and reconcile.
A strong traceability rule is to keep three layers separate:
- Identifier layer: what item or trade unit is it?
- Event layer: what happened to it and when?
- Status layer: what condition and location is it in now?
When these layers are mixed together, teams start trusting the barcode more than the actual item. In a returns environment, that is a mistake. The physical unit, its condition, and the documented event history must all agree before stock is considered usable again.
Operational Controls to Prevent Duplicate Movement
Duplicate return processing usually comes from three sources: retry after timeout, double-clicking by staff, and repeated webhook delivery from an external system. The control response should be the same in all three cases: the transaction must be recognizable as already handled.
Use a unique document reference or idempotency key per return event. That reference should point to the original source document, the original line item, and the specific movement action. If the same request arrives twice, the second request should confirm the existing result instead of creating a new stock movement. This is especially important when a return triggers both inventory actions and financial actions.
Managers should ask the following before approving automation:
- Can one return event create only one movement per item line?
- Can duplicate requests be detected by reference?
- Are status transitions locked once completed?
- Can a partial return be reopened safely without duplicating the credit?
- Is there an event ledger or audit trail that shows who changed what and when?
In practice, the safest design is to treat every return as a recorded event with a unique identity and a clear final state. That way, whether the item ends up sellable, open-box, damaged, repair, supplier return, quarantine, or scrap, the business can explain exactly why the quantity changed and why the financial document changed only once.
Why returns management must end with reconciliation, not just receiving
In a small retail operation, a returned item can look “finished” the moment it arrives back at the counter. In practice, that is only the beginning. A proper inventory returns process ends when the physical item, the stock record, and the accounting record all agree. If those three layers do not match, the business will eventually see unexplained shortages, overstated stock, or refunds issued for goods that were never verified.
For a Georgian retail business with a shop in Tbilisi, a warehouse on the outskirts, and a repair desk handling network equipment, returns management must separate four things very clearly: the physical return, the financial refund decision, the inventory disposition, and the document trail. Rigi24 can support inventory items, warehouses, locations, stock counts, stock movements, repair, damage, and scrap concepts, but any deeper process such as refund automation or integrated returns must be treated as a business workflow decision, not assumed system behavior.
Three-step sign-off: receiving, finance, and inventory supervisor
A robust sign-off sequence reduces arguments later. The ideal flow is simple: receiving confirms what arrived, finance confirms what should be credited or reversed, and the inventory supervisor confirms where the item belongs in stock or disposition. Each step should leave a record, and each step should be able to reject the return if something does not match.
Step 1: receiving verifies the physical return
At the warehouse or shop back office, the receiving clerk checks the returned item against the source document. The clerk should record item name, SKU or internal code, serial number if used internally, quantity, visible condition, packaging state, and the reason stated by the customer or store staff. If the item is incomplete, the clerk must not assume the missing component will arrive later. The record should say exactly what was received today, not what is expected in theory.
Example: a customer returns one network switch with a missing power adapter. The receiving clerk records one unit received, “accessory missing,” and attaches photos of the box contents. That is not yet a decision about resellability; it is only confirmation of what physically arrived.
Step 2: finance confirms the monetary treatment
Finance should work from the accepted return document, not from a verbal promise made at the counter. The team must confirm whether the case is eligible for a full refund, partial refund, store credit, replacement, or no refund pending inspection. Even in a simple operation, this step prevents a common failure case: a refund is issued before the warehouse confirms that the item is present and in acceptable condition.
For example, if a router sold for 420 GEL is returned with damaged packaging but the unit itself is working, finance may approve a partial value adjustment only if the company policy allows it. If the item is later found to be missing parts, that financial decision may need to be amended. The key is that finance records the decision and the basis for it.
Step 3: inventory supervisor signs the disposition
The inventory supervisor decides the item’s stock destination: back to sellable stock, quarantine, repair, damage, scrap, or supplier return queue. This is the point where the physical and accounting sides meet. If the item is restockable, the supervisor authorizes movement back into usable stock. If it is not, the item should move to damage or scrap with a clear reason code and date.
In Rigi24 terms, the supervisor’s decision should be represented as a controlled stock movement and a documented status change where the operation is actually supported. If the business needs a separate approval note, that note should be attached in the workflow or maintained in a document system. The important principle is not the software label; it is the ability to show who decided what, when, and why.
What the audit trail must capture
An audit trail is not just a log of edits. It is the business memory of the return. If a dispute appears three weeks later, management should be able to answer five questions without guessing: who handled it, what changed, why it changed, when it changed, and what evidence supported the decision.
Core fields for every return decision
- Employee name and role — receiving clerk, finance officer, inventory supervisor, or repair technician.
- Timestamp — date and time of receipt, review, approval, and final movement.
- Original quantity and adjusted quantity — for example, 3 returned, 2 accepted, 1 rejected.
- Reason code — incomplete, wrong product, opened, damaged, no proof of purchase, late arrival after refund, and similar operational reasons.
- Condition notes — sealed, opened, scratched, tested, missing accessory, non-functional.
- Evidence attached — photos, receiving form, customer note, repair report, transport receipt, or warehouse transfer note.
Why timestamps matter in practical disputes
Consider a customer who returns a laptop adapter and later claims the item was accepted by the shop, but the warehouse says it never arrived. Without timestamps, the business cannot tell whether the item was misrouted, delayed, or never handed over. With timestamps, the team can see that the shop received the item at 11:20, the warehouse checked it at 16:10, and the finance note was made the following morning. That sequence can clarify whether the issue was delay, loss, or process failure.
Audit trails also help when multiple employees touch the same case. If one employee marks an item as “usable” and another later changes it to “scrap,” the log must show the reason for the change. A silent override is a weak control; a documented override is manageable.
Warehouse and accounting reconciliation without double updates
The biggest operational risk in returns is a double update: the item is adjusted in stock once when received, and again when approved for return disposition, but the accounting side is also changed twice or in the wrong order. This creates phantom stock or duplicate financial effects. The cure is sequence discipline.
Recommended reconciliation sequence
- Receive the returned item and create a single intake record.
- Inspect and classify condition.
- Record the accounting decision only after the return is accepted by policy.
- Post inventory movement only once the final physical destination is known.
- Match the source document, the stock movement, and the financial note before closing.
As a practical example, a warehouse in Tbilisi receives four returned access points from a shop in Kutaisi. Two are sealed and resellable, one is opened but functional, and one is physically damaged. The receiving team logs four items. Finance records the monetary treatment according to company policy. The supervisor then splits the items into sellable stock, repair, and damage. If each step is performed once and in order, reconciliation becomes a routine review instead of a detective exercise.
Detailed return cases and the decisions they force
Incomplete return: the box is back, the full set is not
This is one of the most common failure cases. A customer returns a camera, router, or printer but omits cables, manuals, mounting parts, or warranty cards. The business must decide whether to accept the main unit, reject the case, or accept with a partial value adjustment. The decision should depend on the company’s documented policy and the item’s resale impact, not on pressure at the counter.
Operationally, the receiver should mark the item as incomplete, list the missing parts, and add photos. The supervisor can then decide whether the unit goes to repair, discount resale, or scrap. If the missing accessory is inexpensive but essential for resale, the item may be blocked from sellable stock until completed or reconditioned.
Wrong product: returned item does not match the sale
Sometimes the wrong product is returned intentionally, and sometimes the customer is genuinely mistaken. The workflow must be the same either way. Compare SKU, packaging, color, model number, and if used internally, serial or batch identifiers. If the item does not match the sale, do not mix it into the original transaction as if nothing happened.
Example: a customer bought a 16-port switch but returns an 8-port switch in the same box. The receiver records “wrong product received” and stops there. Finance should not approve a credit against the original sale until the item mismatch is resolved. The supervisor may route the item to hold status while the store contacts the customer.
Goods received after refund
This case is especially risky because the financial side has already moved. A refund may have been issued because the item was promised but not yet physically back, and then the package arrives later. The first rule is to keep the physical receipt separate from the refund status. The second rule is to avoid duplicate financial actions.
If the item arrives after the refund, the warehouse still needs to inspect it and record condition. Then the business decides whether the item can be resold, repaired, or scrapped. The accounting team should not “refund again” or create a second correction simply because the item finally arrived. Instead, the later physical receipt should be reconciled against the already-closed financial case.
Warehouse in a different city
When the shop is in Tbilisi and the warehouse is in another city, transport time becomes part of the return process. The store may physically accept the item, but inventory should not be updated as sellable stock until the warehouse confirms receipt and condition. This is where a transfer trail is essential.
A practical rule is to treat the item as in-transit until the receiving warehouse signs it in. If the item travels from a store in Batumi to a warehouse near Tbilisi, the log should show when it left the store, who packaged it, who transported it, and who received it. If the item is damaged in transit, the audit trail should show whether the damage was pre-existing or transport-related.
Recurring customer issues
Some customers repeatedly return the same categories of goods: cables that fail early, accessories with missing pieces, or devices chosen with the wrong specification. These patterns are valuable, but they must be measured carefully. Repeated returns from one customer may indicate misuse, poor product explanation, or a packaging problem. They do not automatically prove fraud.
Management should review the reasons by customer, product family, and store location. If the same product line shows repeated “wrong product” returns, the issue may be shelf labeling or staff recommendation quality. If the same customer repeatedly returns opened network equipment, the business may need a stricter check-in procedure or a pre-sale compatibility checklist.
Returns KPIs that help managers see what is really happening
Returns should be measured with practical, non-fancy indicators that connect to real work. No benchmark is useful unless the team understands the calculation and the data source. A KPI is only meaningful if the inputs are clean.
| KPI | What it measures | Simple calculation idea |
|---|---|---|
| Return rate | How many sold items come back | Returned units divided by sold units for the period |
| Time to disposition | How long it takes to decide the final status | Days or hours from receipt to final approval |
| Restock time | How long usable items stay blocked before returning to sellable stock | Receipt to stock-available movement |
| Resellable recovery | Share of returned units that become sellable again | Sellable returns divided by total accepted returns |
| Damage share | How much of the return flow is damaged | Damaged units divided by all returned units |
| Error and shrinkage | Unexpected losses or mis-postings linked to returns | Adjustments not explained by accepted workflow |
These KPIs should be reviewed separately for shop, warehouse, and repair desk activity. A repair-heavy product line may naturally have longer disposition time, while sealed accessories may move back to stock quickly. The point is not to force one universal number, but to observe whether the process is drifting.
How a small Georgian retail operation can train the team
A useful training exercise should be practical enough for a small business with limited staff. Use three roles: one shop associate, one warehouse receiver, and one repair desk technician. Give them five sample returns and ask them to process each one from beginning to end.
- Case A: a sealed network cable returned unopened.
- Case B: a Wi-Fi router returned with a missing power adapter.
- Case C: a switch returned as the wrong model.
- Case D: a printer accessory arrives after the refund decision.
- Case E: a device with visible physical damage and no clear customer explanation.
Ask the team to complete the following tasks for each case: identify the source document, record the received quantity, decide whether evidence is sufficient, choose a disposition, and note what must be reconciled in inventory and accounting. Then review the log for missing timestamps, missing reasons, or duplicate stock updates. This exercise reveals whether the team truly understands the difference between “returned,” “accepted,” “refundable,” and “resellable.”
First week, first month, and quarterly inspection checklist
First week
- Confirm that every return has a source document or intake note.
- Require a visible reason code on each case.
- Check whether receiving, finance, and inventory supervisor sign-offs are separate.
- Review three recent cases for evidence attachments and timestamp accuracy.
- Ensure staff know that physical return and refund are not the same event.
First month
- Compare received quantities with final disposition quantities for mismatches.
- Review all partial returns and incomplete returns for consistency.
- Check whether warehouse transfers between cities are documented cleanly.
- Measure time to disposition and restock time for the main product groups.
- Look for repeated errors such as double updates, missing photos, or unapproved stock movements.
Quarterly inspection
- Sample returns from shop, warehouse, and repair desk.
- Audit audit-trail completeness: who, what, when, why, evidence.
- Review shrinkage or unexplained adjustments linked to returns.
- Test whether the team still distinguishes usable stock from damaged or scrap stock.
- Update the workflow if a recurring failure case appears more than once.
What Rigi24 can support versus what must remain a business rule
Rigi24 includes inventory items, warehouses, locations, stock counts, stock movements, repair, damage, and scrap concepts, and it also has separate online-store and invoice modules. That makes it useful for tracking stock and operational states. However, do not assume it automatically performs returns processing, partial line returns, refund automation, payment processing, integrated returns handling, serial tracking, event deduplication, or automatic synchronization unless that has been independently verified in your own implementation.
In practice, that means the business should define the return workflow first and then decide which steps are recorded in the system and which steps are handled manually or in another tool. Best practice is to create a clear workflow map: intake, inspection, decision, stock movement, finance review, and final closure. If a feature exists in your deployment, it should be confirmed by testing, not assumed from the category name.
Concise decision checklist and grounded next steps
- Is the physical item present and counted correctly?
- Does the item match the original sale or source document?
- Is the condition fully recorded, including missing parts and damage?
- Has finance made a documented decision separate from receiving?
- Has the inventory supervisor assigned the final disposition?
- Are timestamps, reasons, and evidence attached?
- Has the stock movement been posted only once?
- Is the item clearly marked as sellable, repair, damage, scrap, or in transit?
Next step: choose five recent returns and reconcile them end to end. If the team cannot explain one case without searching through messages, the process is still too informal. Tighten the sign-off sequence, standardize the reason codes, and require evidence before any final adjustment. That is the fastest path to cleaner stock, cleaner accounts, and fewer disputes.
Frequently asked questions
Can a customer return only part of one invoice line?
The returned quantity should be tied to the original invoice line; the specific software workflow must be verified separately.
Should damaged goods automatically become sellable stock?
No. Inspection and disposition should precede any increase to sellable quantity.
How is a physical return different from a refund?
Receiving goods and returning money are separate events that must be reconciled.
How should partial returns be recorded?
Tie each returned quantity to the original sale document and line.
What happens to items requiring repair?
Quarantine them away from sellable stock pending inspection and disposition.
How do we prevent duplicate stock adjustments?
Use a unique return reference and check the movement ledger before posting.
What if a return arrives at a different branch?
Record the actual receiving location and any necessary transfer.
Which evidence should be retained?
Keep the original sale reference, inspection decision and receiving history.
 Practical inventory counting resourcesWarehouse Stocktaking and Cycle Counting: How to Resolve Inventory Discrepancies
 Employee communicationTeam Chat for Employees: Private and Group Messaging | Rigi24
 Tasks and remindersWorkspace and Task Management for Small Teams | Rigi24
Related practical resourcesInventory Returns Management: Partial Returns, Damaged Goods and Stock Reconciliation